

Quarterly Economic and Market Review
- Fed Hike in September — The Federal Reserve hiked their policy rate by 25 basis points in September as their focus is centered on moving inflation back toward 2%.
- Equity Markets Mixed, Bonds Down — Longer term interest rates moved higher at the end of the quarter, leading to broad losses in bond markets. Equity markets produced mixed results, led by the S&P 500.
- Economy Resilient, but Rates Are a Risk – While underlying fundamentals (i.e. consumer wealth and spending, labor markets, investment growth) remained positive, the cost from higher interest rates could slow economic momentum.
Fed hikes, focused on inflation
At the start of 2026, the Federal Reserve (Fed) was widely expected to continue gradually lowering its policy interest rate after cutting it by 0.25% three times last year. Instead, rising urgency around inflation has taken hold. On September 16, the Fed raised its benchmark interest rate by 25 basis points to a range of 3.75% to 4.00% – the first hike since 2023. Another 25-basis point hike is expected by the end of the year. The stated reasons include continued economic expansion, a stable job market with persistently low unemployment and elevated uncertainty largely stemming from geopolitical developments (i.e., the Iran war and resulting energy supply chain disruption). Against that backdrop, the Fed’s primary goal is a “timelier return to the Committee’s 2-percent goal” from its currently elevated rate.
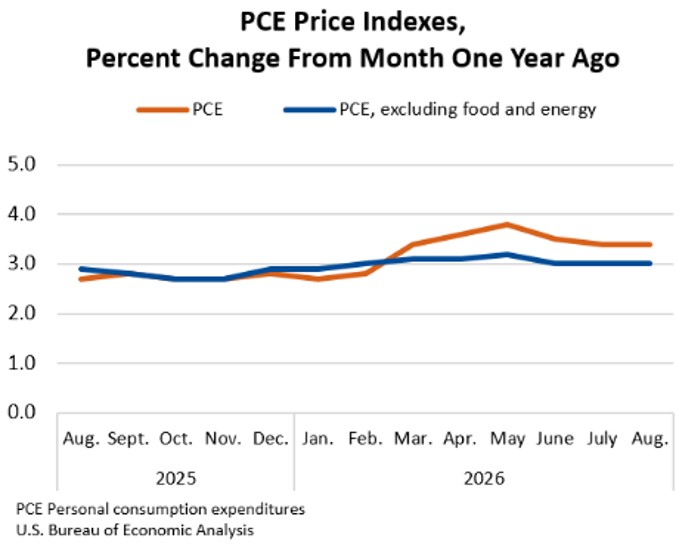
Typically, the Federal Reserve is hesitant to raise interest rates in response to a short-term energy price jump because these episodes can be brief and self-correcting. However, if an energy shock persists, higher energy prices can “seep” into other parts of the economy that rely on fossil fuels as inputs, including plastics, transportation and airfare. At this point, there appears to be very little momentum toward a resolution of hostilities with Iran in the Middle East. Continued disruption of energy supplies, combined with the risk of escalation, is therefore one of the key risks heading into the fourth quarter of 2026
Capital markets faced a challenging quarter
U.S. equities produced mixed results through the quarter against a backdrop of renewed concerns over the conflict in the Middle East and persistent trade uncertainty. Market participation became increasingly narrow. The S&P 500 returned +2.30% for the quarter and reached new all-time highs, yet by late September only about 22% of S&P 500 companies were trading above their 50-day moving averages. Mid-cap stocks fell -6.4% and smallcap US stocks were down -7.9%. Much of the positive market breadth seen during the first half of the year had eroded, with gains increasingly concentrated among large-cap firms, led by strength in Energy companies and a recovery among AI-adjacent players.
Corporate fundamentals remained a key source of market support. Second quarter earnings results reported during the period were particularly strong, with 78% of S&P 500 companies exceeding earnings expectations. Earnings increased 53% from a year earlier, with AI investment and strong consumer spending among the top contributors to results.
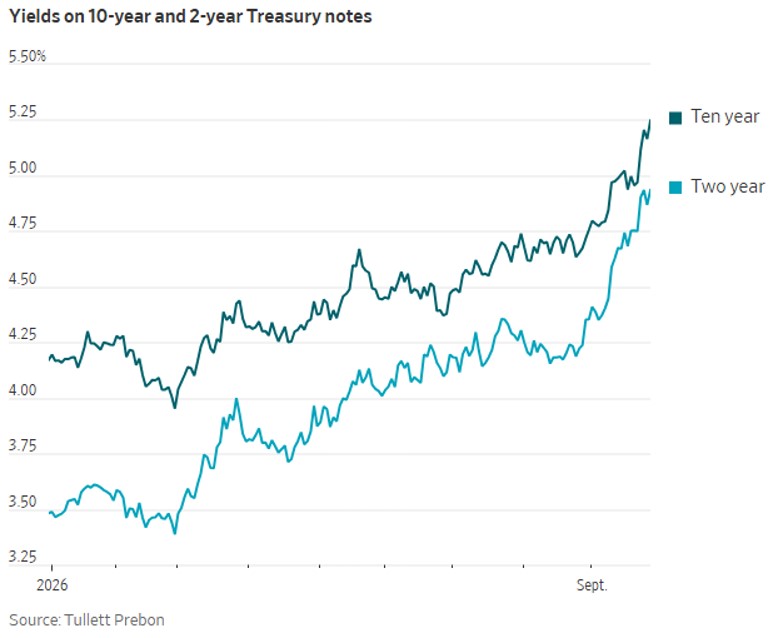
Taken together, underlying capital market performance was considerably more mixed than headline indexes suggested. Higher yields pressured rate-sensitive assets and tightened financial conditions, while elevated energy prices and weakening consumer fundamentals raised additional concerns about the durability of economic growth.
Potential impact of rising rates on economy
Higher interest rates tend to affect the economy with a delay, and the most rate-sensitive areas have already begun to react. The bond market has seen prices fall, while in housing, inventory has climbed and closings have fallen, leading to increasing price concessions. The broader question is how equity markets and the economy will respond as the effects of higher rates spread. Recent history provides some reason for resilience: recessions were avoided when the Fed raised its policy rate from 0% to 5.25% from 2022-2023, in 2025 when President Trump enacted the significant tariff regime and again this spring with the initiation of hostilities in Iran and the beginning of the energy supply crunch. Markets suffered – sometimes significantly – during these events, but recoveries were swift, and through it all economic fundamentals continued to trend positive.
Current economic data also point to continued growth. Second quarter real GDP growth was revised up to +2.2%, while the Fed’s own modeling projects third quarter real GDP growth to be even stronger, at +3.7%. Growth has continued to come from the two largest components of GDP – consumption and investment. Consumer spending added approximately +2.5% to real GDP growth in the second quarter, and the trend looks durable, with August consumer spending rising +0.9%. The continued stability of the labor market provides additional support: the unemployment rate stands at 4.2%, and the last time unemployment was below 5% for this long was in the 1960s.
Investment spending contributed +1.25% to second quarter growth. Of that, the $800 billion in business capital expenditures being spent this year on artificial intelligence-mostly datacenter investment - is adding roughly +0.5%. Numerous bottlenecks loom, including local political pushback, safety concerns that could lead to a voluntary slowdown in development and the extraordinary energy demand required to accommodate planned data centers. For now, however, there is little sign from either the hyperscalers making these investments or the companies providing the equipment and chips that this spending is set to decline in the near term.
Sustained high interest rates will raise costs for both consumers and businesses. Whether this additional pressure is enough to crack such a resilient economy will likely be the primary focus heading into the end of the year
Investment, Securities and Insurance Products:
NOT
FDIC INSUREDNOT BANK
GUARANTEEDMAY
LOSE VALUENOT INSURED BY ANY
FEDERAL AGENCYNOT A
DEPOSITAssociated Bank and Associated Bank Private Wealth are marketing names Associated Banc-Corp (AB-C) uses for products and services offered by its affiliates. Securities and investment advisory services are offered by Associated Investment Services, Inc. (AIS), member FINRA/SIPC; insurance products are offered by licensed agents of AIS; deposit and loan products and services are offered through Associated Bank, N.A. (ABNA); investment management, fiduciary, administrative and planning services are offered through Associated Trust Company, N.A. (ATC); and Kellogg Asset Management, LLC® (KAM) provides investment management services to AB-C affiliates. AIS, ABNA, ATC, and KAM are all direct or indirect, wholly-owned subsidiaries of AB-C. AB-C and its affiliates do not provide tax, legal or accounting advice. Please consult with your advisors regarding your individual situation. (1024)
Readers should not consider this update of the economic and investment environment as analysis upon which to make investment decisions or recommendations of strategies or particular securities. Past performance is no guarantee of future results. (1414)
All trademarks, service marks and trade names referenced in this material are the property of their respective owners.
