

Monthly Interest Rate Update
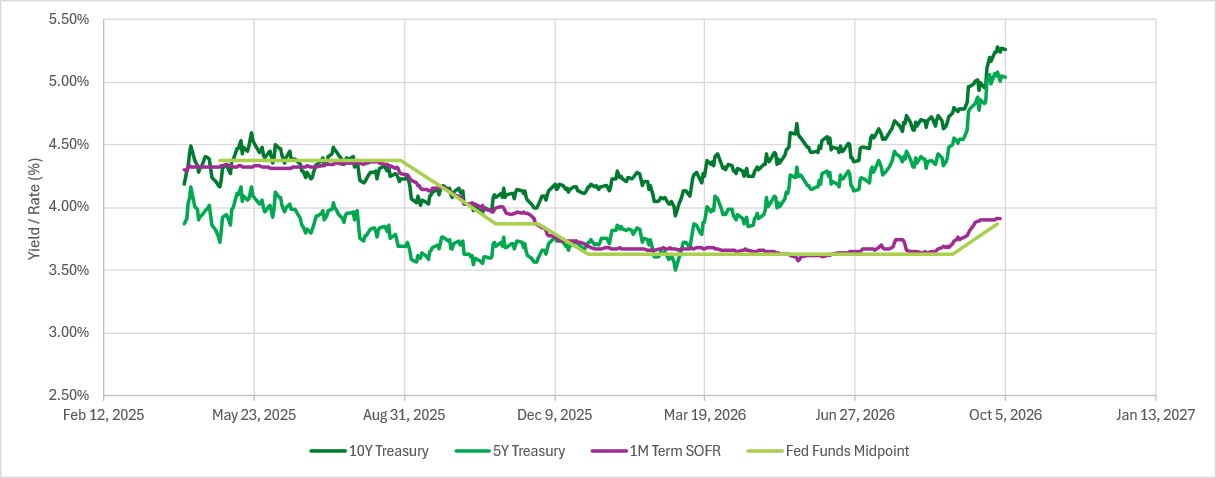
The US 10-year Treasury yield climbed to 5.28% as of September 30, up from 4.80% at the start of the month, reaching its highest level since 2007. Key drivers of higher rates continue to be elevated oil prices; expectations of more Federal Reserve tightening in response to stubborn inflation; resilient economic growth; and a growing supply of Treasury bonds and corporate debt. With 5- and 10-year yields surpassing the psychologically important 5% level, the bond sell-off threatens to create a self-reinforcing cycle of upward momentum.
Relentless rise in rates signals global shift
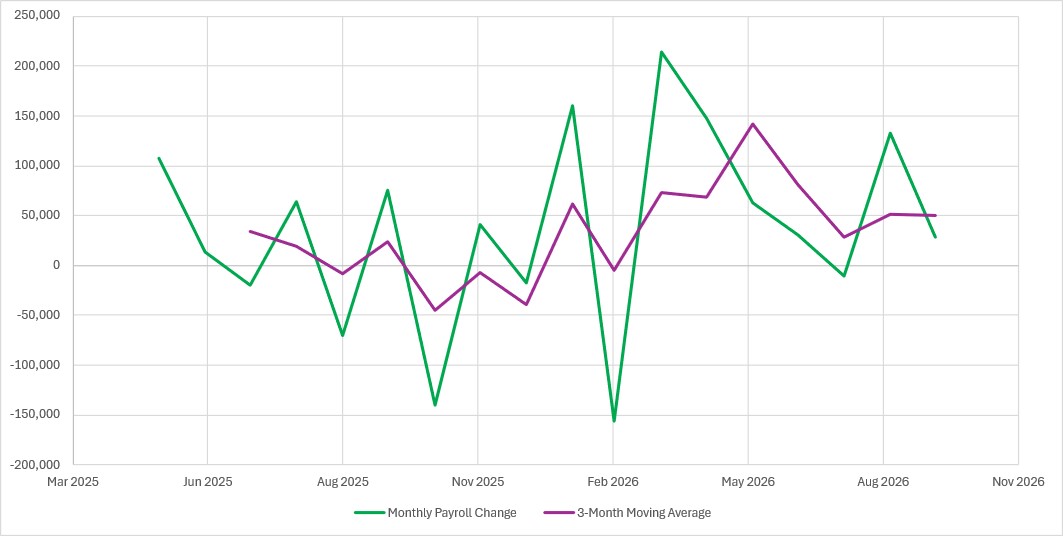
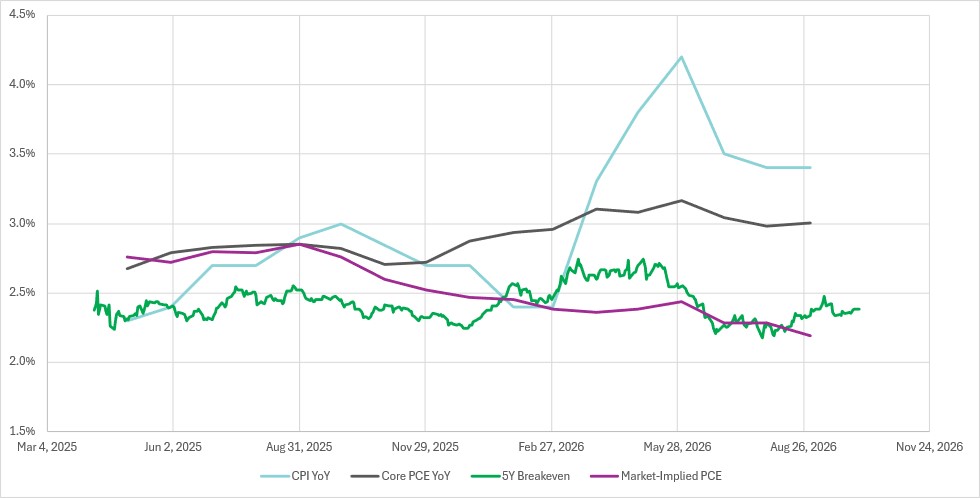
The Federal Reserve raised short-term rates for the first time in three years. With inflation stubbornly persistent at 3.4%, the Federal Open Market Committee hiked rates a quarter-point in September, consistent with Fed Chair Warsh’s signals in August. This was the first upward move since the end of the aggressive 2022-2023 tightening cycle and it pushed the benchmark floating rate SOFR index to 3.92%. Futures traders are now pricing in an additional 75 bp of hikes by June, though tepid September job creation and a small uptick in unemployment to 4.2% this month suggests the Fed may have some room for patience.
Rising commodity prices are contributing to inflationary pressures. Led by oil, where Brent crude has again pushed above $100 per barrel, commodity prices continue to move higher. Prices are under pressure across the energy complex, with diesel over $5 per gallon, while natural gas and coal face supply disruptions and steady demand. In metals, copper hit all-time highs in September, while aluminum is headed for a 4-year high as smelter capacity is compromised due to the Iran conflict.
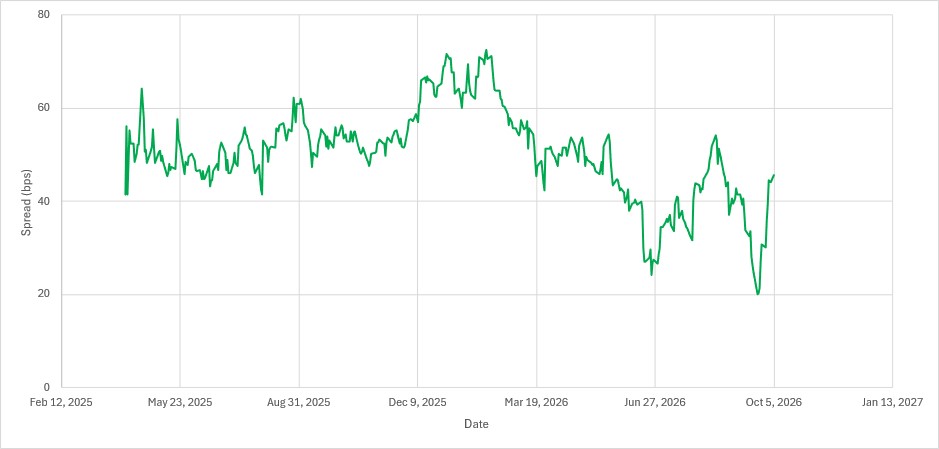
Long term rates have returned to pre-Great Recession levels, bursting past their 2023 peaks to reach 19-year highs. A combination of factors, including persistent government deficits, record bond issuance in both the investment grade and high yield sectors, and solid economic growth, have led investors to adjust their long run rate expectations higher. Notably, markets have not materially raised their implied inflation outlook, as measured by TIPS breakevens, nor have credit spreads widened. The yield curve remains relatively flat as well, with the spread between 2- and 10-year Treasuries hovering near 45 bp. Instead, there has been an idiopathic upward shift, with a broad-based consensus building that the liquidity glut in the wake of the Great Recession and the pandemic has now been spent and rates should return to the prior status quo. This reassessment is showing up in higher corporate borrowing costs and elevated consumer lending rates, including 30-year mortgage rates above 7.25%.
The move toward higher rates is also a global phenomenon. It reflects the worldwide impact of higher energy prices from the wars in Iran and Ukraine, the disruptive effects of tariffs on international trade and the competing demands for capital from governments—who are raising defense spending and absorbing the costs of trade wars—and from AI hyperscalers tapping into global financial markets to fund the AI buildout.
Key Statistics: Benchmark rates, Unemployment and Inflation
| Year-end 2023 | Year-end 2024 | Year-end 2025 | September 30, 2026 | |
|---|---|---|---|---|
| 10-yr Treasury yield | 3.88% | 4.57% | 4.17% | 5.28% |
| 2-yr Treasury yield | 4.25% | 4.24% | 3.47% | 4.89% |
| Spread | -0.37% | 0.33% | 0.70% | 0.40% |
| Fed Funds Target (mid) | 5.375% | 4.375% | 3.625% | 3.88% |
| CME Term SOFR 1-mo | 5.35% | 4.33% | 3.69% | 3.91% |
| CPI (y/y change) | 3.1% | 2.7% | 2.7% | 3.4% |
| Core PCE (monthly) | 3.16% | 2.81% | 2.83% | 3.0% |
| 5-yr TIPS (market breakeven) | 2.15% | 2.39% | 2.27% | 2.38% |
| U-3 Unemployment | 3.7% | 4.1% | 4.4% | 4.2% |
| 12-month Change in Nonfarm Payrolls | +2,560,000 | +1,450,000 | +371,000 | +496,000 |
Benchmark Interest Rates – past 18 months
Source: Bloomberg Finance LP
- Long term rates surge—Markets have been pushing long-term rates higher, helping to prompt the FOMC to raise rates a quarter-point after 66 months of above-target inflation.
Non-Farm Payrolls: tepid growth
Source: Bloomberg Finance LP
US Inflation Data: Still elevated, but market worries wane
Source: Bloomberg Finance LP
US Treasury Yield Curve: 2-10 spread remains flat
Associated Bank offers a wide range of instruments for hedging interest rate, commodity and foreign currency risk, including foreign exchange in more than 75 currencies. Companies interested in learning more about these instruments should contact their Associated Bank Relationship Banker or the bank’s Capital Markets Department at 866-524-8836.
All rates shown are indications only and subject to change.
This material is provided to you for informational purposes only; and any use for other than informational purposes is disclaimed. It is a summary and does not purport to set forth all applicable terms or issues. It is not intended as an offer or solicitation for the purchase or sale of any financial product and is not a commitment by Associated Banc-Corp, its subsidiaries or affiliates, as to the availability of any such product at any time. The information herein is not intended to constitute legal, tax, accounting, or investment advice, and you should consult your own advisors as to such matters and the suitability of any transaction. We make no representations as to such matters or any other effects of any transaction. In no event shall we be liable for any use of, for any decision made or action taken in reliance upon, or for any inaccuracies or errors in, or omissions from, the information herein. The views expressed here are solely those of the author and do not reflect the views of Associated Banc-Corp, its subsidiaries or affiliates.
